Contents · 8 sections
The process of importing goods into Morocco.
Importing goods into Morocco is governed by precise customs, tax and regulatory rules. Poor planning can lead to delays, extra costs or goods being held at customs.
Understanding the import process, Incoterms, documentary requirements and customs checks is therefore essential to secure your operations and optimise your costs.
The customs procedure: a structured control system
The customs administration applies a selectivity system to check imported goods and determine the duties and taxes due.
The customs declaration (DUM)
Every import requires a Single Goods Declaration (DUM):
- filed by an approved customs broker in BADR, the customs administration’s IT system; prior formalities, such as the import licence, go through the PortNet single window;
- it states the origin, value and nature of the goods.
This declaration is the basis for calculating duties and taxes.
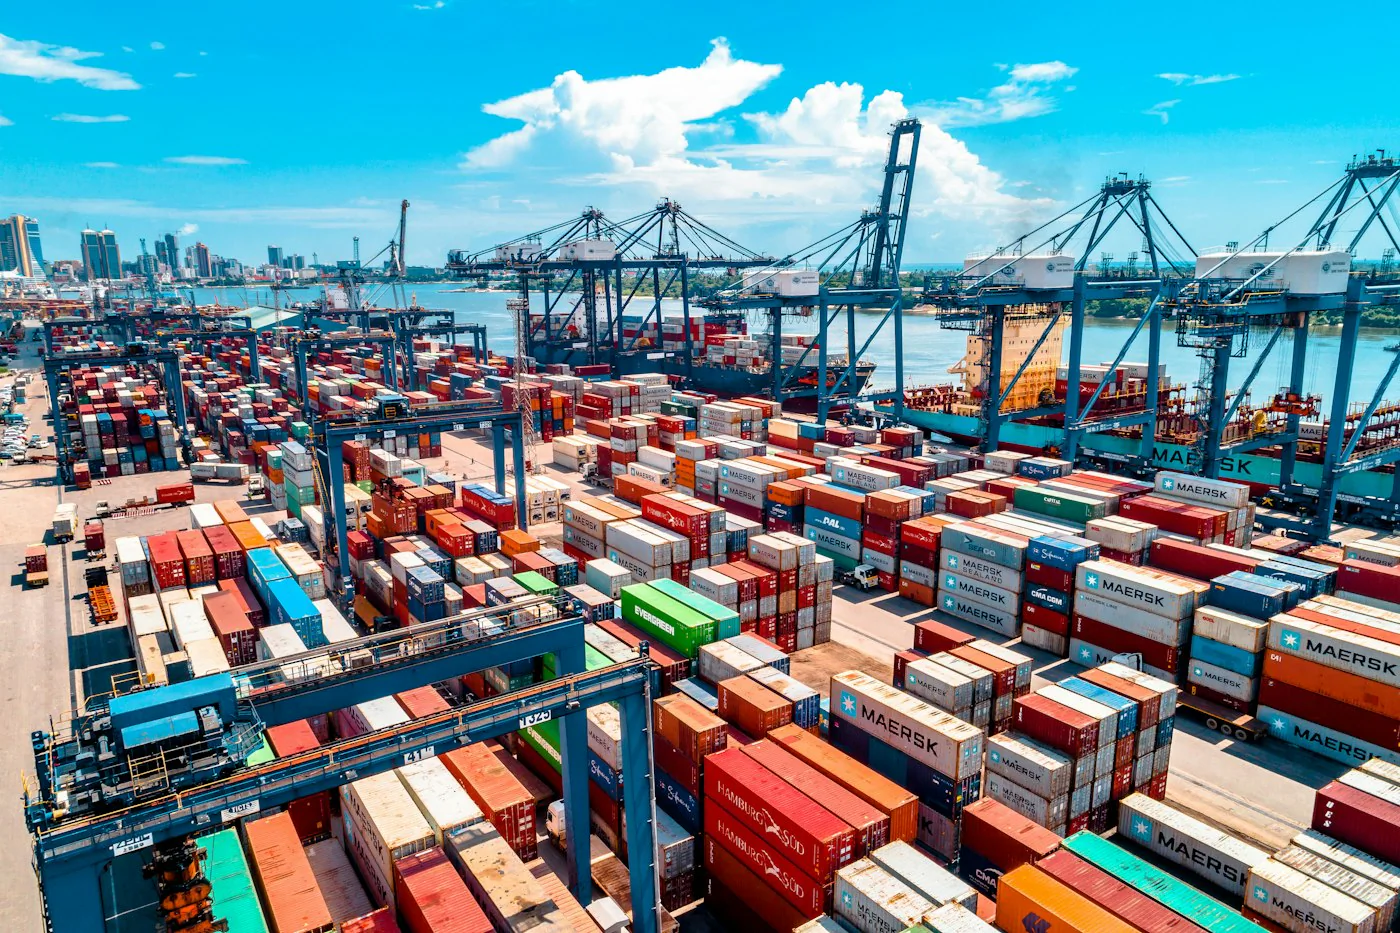
Customs selectivity channels
Once the DUM has been filed, customs directs the file to one of the following channels:
- Green channel: automatic release without inspection
- Orange channel: documentary check
- Red channel: physical inspection of the goods
The level of control depends in particular on the nature of the goods, the importer’s track record and the level of risk identified.
Assessment of duties and taxes
Once the goods have been checked, customs assesses the duties and taxes:
- Import duties (DI) according to the HS code
- Import VAT: 20% at the standard rate, or a reduced rate for certain products under the General Tax Code
- Specific taxes, where applicable:
- Domestic consumption tax (TIC)
- eco-taxes
- parafiscal levies
Correct tariff classification is decisive in avoiding any reassessment.
The role of Incoterms in importing
Incoterms set out how costs, responsibilities and the transfer of risk are shared between buyer and seller. They have a direct impact on the overall cost of the import.
The most widely used Incoterms
- EXW (Ex Works):
The buyer bears all costs and risks from the moment the goods leave the seller’s factory. - FOB (Free On Board):
The seller bears the costs up to the port of shipment. Risk transfers at loading. - CIF (Cost, Insurance and Freight):
The seller pays for transport and marine insurance. Risk transfers at loading. - CIP (Carriage and Insurance Paid To):
The seller pays for transport and comprehensive insurance. Risk transfers when the goods are handed to the carrier. - DDP (Delivered Duty Paid):
The seller bears all costs and formalities up to final delivery at the buyer’s premises.
The choice of Incoterm should match the company’s level of logistical and financial control.
Foreign suppliers: 5 points to check before importing
Before any import, it is essential to secure the relationship with the foreign supplier:
- Supplier reliability
Track record, references, customer reviews and certifications. - Product compliance
Compliance with Moroccan standards: VoC, ONSSA, ANRT, depending on the nature of the goods. - Chosen Incoterm
Clearly identify who pays for what and when risk is transferred. - Secure payment
Choice of payment method according to the level of trust:
TT, CAD or documentary credit (LC). - Mandatory documents
- Commercial invoice
- Packing list
- Certificate of origin
- Bill of Lading or Air Waybill
A missing or incorrect item can lead to goods being held at customs.
Conclusion
Importing goods into Morocco relies on close coordination between customs procedures, logistics choices and regulatory compliance.
Mastering Incoterms, the required documents and tax obligations helps secure flows, optimise costs and avoid operational risks.
Professional support often makes the difference in structuring import-export operations effectively and ensuring customs compliance.